If you’ve started looking into carbon reporting, you’ve probably come across Scope 1, 2 and 3 emissions.
In simple terms, the three Scopes are a way of grouping the greenhouse gas emissions associated with a business.
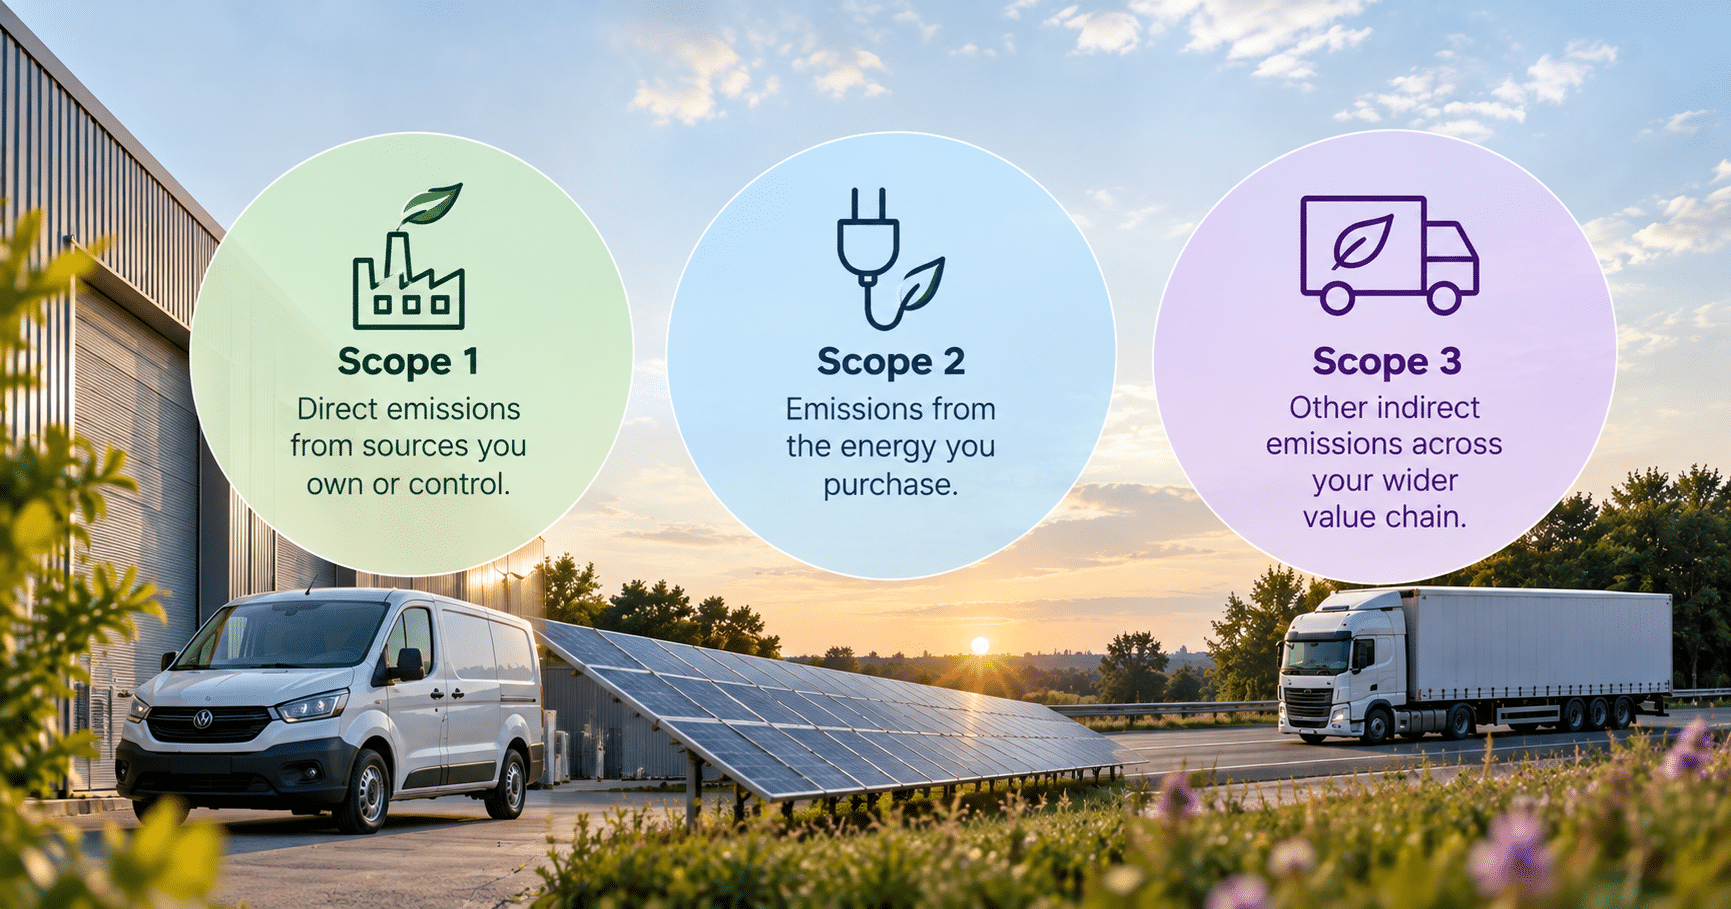
- Scope 1 covers emissions from sources your business owns or controls.
- Scope 2 covers emissions associated with the energy your business purchases.
- Scope 3 covers other indirect emissions connected to your business and its wider value chain.
Which emissions apply to your organisation will depend on how your business operates and why you’re measuring them. This guide explains what the three Scopes mean, how they fit together and where they might appear in a typical UK business.
What are Scope 1, 2 and 3 emissions?
The three Scopes provide a framework for categorising the greenhouse gas emissions associated with an organisation.
A simple way to think about them is:
Scope 1 – direct emissions
These are emissions from sources that your organisation owns or controls.
Examples include:
- Fuel used in boilers or heating systems
- Fuel used in company-owned or controlled vehicles
- Generators
- Some industrial processes
- Refrigerant or other fugitive emissions
Scope 2 – purchased energy
These are indirect emissions associated with energy your organisation purchases.
For many businesses, this will mainly mean electricity.
Purchased heat, steam or cooling can also fall within Scope 2 where relevant.
Scope 3 – other indirect emissions
These are emissions associated with activities across your wider value chain that aren’t included in Scope 1 or Scope 2.
Examples can include:
- Purchased goods and services
- Business travel
- Employee commuting
- Waste
- Transportation and distribution
- Capital goods
- Use of sold products
- End-of-life treatment of sold products
Scope 3 is divided into 15 categories, although not every category will apply to every business.
Scope 1 vs Scope 2 vs Scope 3
The easiest way to see the difference is:
| Scope | What it covers | Examples |
| Scope 1 | Direct emissions from sources your business owns or controls | Gas heating, company vehicles, generators |
| Scope 2 | Indirect emissions associated with purchased energy | Electricity, purchased heat or steam |
| Scope 3 | Other indirect emissions across your value chain | Purchased goods, travel, waste and transportation |
The three Scopes aren’t three separate carbon footprints.
They are a way of organising the emissions associated with your organisation.
What are Scope 1 emissions?
Scope 1 emissions come directly from sources owned or controlled by your organisation.
For some businesses, this may be relatively straightforward.
For example, a business could have Scope 1 emissions from:
- Natural gas used for heating
- LPG or other fuels
- Company-owned vehicles
- Generators
- Manufacturing equipment
- Refrigerant leaks
A business with a vehicle fleet may have a different Scope 1 profile from a small office-based company.
A manufacturer may also have direct emissions from its production processes.
The important point is that Scope 1 relates to direct emissions from sources your organisation owns or controls.
For more detail, see our guide to What Are Scope 1 Emissions?
What are Scope 2 emissions?
Scope 2 emissions are associated with the energy your organisation purchases.
For many businesses, purchased electricity will be the main consideration.
That could be electricity used for:
- Lighting
- Computers and office equipment
- Machinery
- Heating and cooling
- Electric vehicle charging
- Other equipment and infrastructure
The emissions aren’t produced directly at your premises. They are associated with the generation of the energy your business purchases.
Purchased heat and steam can also fall within Scope 2 where they are relevant.
For more detail, see our guide to What Are Scope 2 Emissions?
What are Scope 3 emissions?
Scope 3 covers indirect emissions across your wider value chain.
This is often the broadest of the three Scopes because it can include activities outside your direct control.
For example, a manufacturer might need to consider emissions associated with:
- Materials it purchases
- Equipment it buys
- Transportation
- Business travel
- Employee commuting
- Waste
- Products it sells
- How those products are used
- What happens to them at the end of their life
The GHG Protocol divides Scope 3 into 15 categories covering both upstream and downstream activities.
Not every category will apply to every organisation.
A professional services business will have a very different Scope 3 profile from a manufacturer, construction company or logistics business.
That’s why Scope 3 needs to be considered in the context of how a particular business operates.
For a more detailed look at Scope 3, see our guide to Scope 3 emissions.
Which Scope 3 emissions apply to my business?
This is one of the areas businesses often find confusing.
There isn’t one list of Scope 3 emissions that applies to every organisation.
The relevant categories depend on what your business buys, sells and does.
For example, a business may need to consider:
- Purchased goods and services
- Capital goods
- Business travel
- Employee commuting
- Waste
- Transportation
- Leased assets
- The use of products it sells
Another business may have a completely different set of relevant emissions.
The starting point is therefore understanding how your business operates, rather than trying to measure everything.
Our detailed Scope 3 guide explains the different categories in more detail.
Do businesses need to measure all three Scopes?
Not necessarily.
The right approach depends on why you’re measuring your emissions and what you need the information for.
You may be:
- Measuring your emissions for the first time
- Responding to a customer request
- Preparing information for a tender
- Establishing an emissions baseline
- Tracking emissions over time
- Preparing for a reporting requirement
- Looking for opportunities to reduce emissions
Some organisations may start with Scope 1 and Scope 2.
Others may need to include relevant Scope 3 emissions from the beginning.
Certain procurement requirements can also specify particular emissions that need to be reported. PPN 006, for example, has specific requirements around Scope 1, Scope 2 and relevant Scope 3 emissions for applicable public sector procurement.
If you’re dealing with a specific procurement requirement, see our dedicated PPN 006 Carbon Reduction Plan guide.
The question isn’t necessarily:
“Do I have to measure everything?” It’s “What do I need to measure, and why?”
How do Scope 1, 2 and 3 fit into a carbon footprint?
Your carbon footprint brings together the relevant greenhouse gas emissions associated with your organisation over a defined reporting period.
Scope 1, Scope 2 and relevant Scope 3 emissions provide a framework for understanding where those emissions come from.
In simple terms:
Business activities
↓
Scope 1 + Scope 2 + relevant Scope 3 emissions
↓
Overall carbon footprint
The resulting emissions are generally expressed as carbon dioxide equivalent (CO₂e), which provides a common way of expressing the climate impact of different greenhouse gases.
A carbon footprint can give your organisation a baseline for understanding its emissions and tracking them over time.
If you want to understand more about measuring your organisation’s emissions, see our Carbon Footprint Assessment service.
How are Scope 1, 2 and 3 emissions calculated?
The way emissions are calculated depends on what you’re measuring and what information is available.
At a basic level, emissions calculations use activity data and an appropriate emissions factor.
For example, electricity consumption can be combined with the relevant emissions factor to calculate the associated emissions.
The same principle can be applied to other activities, such as fuel use, travel, waste and transportation.
The detail becomes more involved when calculating different types of Scope 3 emissions.
For a closer look at how business emissions can be calculated, see our guide to Understanding Emission Calculation Methods.
Why is it useful to understand your Scope 1, 2 and 3 emissions?
Knowing your total emissions is useful, but understanding where those emissions come from gives you much more information to work with.
Your emissions data can help you understand:
- Which activities generate emissions
- Which emissions you directly control
- Where emissions sit within your wider value chain
- Where better data may be needed
- Where reduction opportunities might exist
- What information customers or tenders may require
- What you may need to monitor in future
It gives you a clearer picture of what is happening across your business rather than reducing everything to one overall number.
What happens after you’ve measured your emissions?
Measuring your emissions gives you a starting point.
Once you understand where your emissions come from, you can decide what to do with that information.
For some businesses, the next step may be improving data collection.
For others, it could mean identifying opportunities to reduce emissions or developing a Carbon Reduction Plan.
The right next step will depend on your organisation, its objectives and what you need to achieve.
For more information about turning emissions data into a practical reduction plan, see our Carbon Reduction Plan guide.
Scope 1, 2 and 3 emissions: the simple version
If all the terminology still feels like a lot, the simplest way to remember it is:
Scope 1
Emissions from sources your organisation owns or controls.
Scope 2
Emissions associated with the energy your